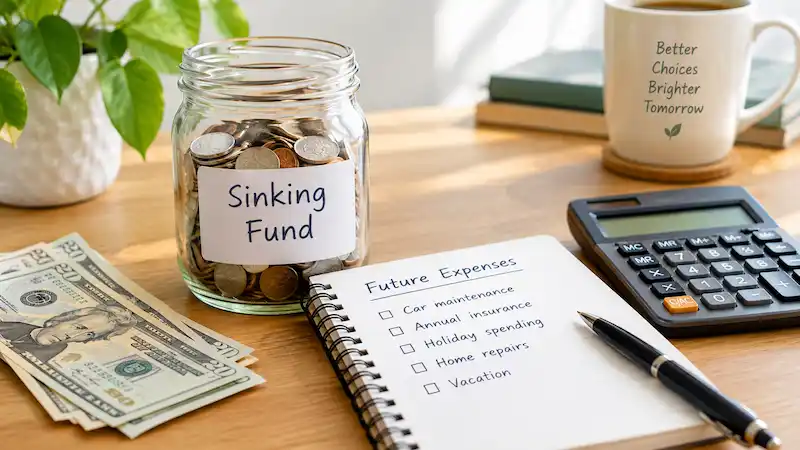
A sinking fund is money you set aside gradually for a known or reasonably expected future expense, so you are not scrambling to cover the full cost when the bill arrives. Instead of finding $1,200 for an annual insurance premium in a single month, you might set aside $100 a month for twelve months.
Sinking funds suit costs you can see coming, such as car maintenance, annual insurance premiums, holiday spending, and planned home repairs. This guide explains how they work, shows the math step by step, and helps you start one that fits your budget.
The term comes from corporate finance, where a company sets cash aside to retire bonds or other debt. AccountingTools notes that individuals can use the same idea to save for a major purchase, such as a car. In personal budgeting, a sinking fund is a method, not a special account or financial product.
How Do Sinking Funds Work?
The process comes down to six steps:
- Identify an upcoming expense.
- Estimate the amount you will need.
- Decide when you will need the money.
- Count how many contributions you can make before then.
- Save a manageable amount at each contribution date.
- Use the accumulated money for the planned expense.
Here is a simple example. Suppose you want $600 for holiday expenses in six months, and you are starting with nothing in the fund. If you make six equal monthly contributions, you need to save $600 ÷ 6 = $100 per month.
This example assumes you can make six contributions before the expense is due. It leaves out interest, fees, withdrawals, and missed contributions, any of which would change the result. It also assumes the cost is predictable, which is rarely perfectly true, so treat your target as your best estimate.
Sinking Fund vs. Emergency Fund
A sinking fund generally covers planned or reasonably anticipated costs. An emergency fund is meant for unexpected expenses or financial disruptions.
| Sinking fund | Emergency fund | |
|---|---|---|
| Purpose | Pay for a planned or reasonably expected cost | Cover unplanned expenses or financial disruptions |
| Typical expenses | Car maintenance, annual premiums, holiday spending, planned repairs | A surprise medical bill, a sudden repair, a loss of income |
| Anticipated? | Yes, or reasonably so | No |
| How the target is set | From a bill, quote, estimate, or past spending, plus a due date | From your own situation and the unexpected costs you have faced before |
| How the money is used | Spent when the planned expense comes due, then often restarted | Used when an unplanned expense or disruption hits, then rebuilt |
The CFPB describes an emergency fund as a cash reserve for unplanned expenses or financial emergencies, and says the right amount depends on your situation. It suggests looking at the unexpected costs you have had in the past to help set a goal. There is no single number that fits everyone.
Some costs sit on the line. Routine car maintenance is predictable, so it fits a sinking fund. A sudden major repair is harder to predict. Depending on your circumstances and budget, you may want both kinds of savings, because a sinking fund does not replace an emergency fund.
Sinking Fund Examples for Your Budget
The figures below are hypothetical planning examples. They are not average costs or recommendations for every household.
| Expense | Target amount | Time remaining | Monthly contribution |
|---|---|---|---|
| Holiday spending | $600 | 6 months | $100 |
| Car maintenance | $900 | 9 months | $100 |
| Annual insurance premium | $1,200 | 12 months | $100 |
| Vacation | $1,500 | 12 months | $125 |
| Anticipated dental expense | $600 | 12 months | $50 |
Replace these numbers with your own estimates, actual bills, quotes, or past spending. Some costs are harder to pin down, like dental work or a home repair. For those, treat the target as an estimate and adjust it when you learn more.
How to Start a Sinking Fund
- List the expenses you expect to pay in the coming months or year.
- Estimate a realistic target for each one.
- Identify the date each amount will be due.
- Subtract any money you have already saved for that specific goal.
- Count the contributions you can make before the deadline.
- Calculate the amount to save per contribution.
- Choose a suitable place to hold the money (more on that below).
- Set up reminders or automated transfers if that suits you. If you automate, keep an eye on your checking balance so a transfer does not trigger overdraft fees.
- Review your progress and adjust targets when costs or circumstances change.
You do not need to fund every possible expense at once. Starting with one or two important upcoming costs is a perfectly good approach, and you can add more as the habit settles in. If you need to rebuild your overall budget first, this financial detox to reset your budget can help you account for irregular expenses.
How Much Should You Save in Sinking Funds Each Month?
Your contribution depends on four things: the target, what you have already saved, the time remaining, and what your budget can handle. The calculation is straightforward:
Required contribution per deposit = max(0, target amount – current balance) / remaining deposits
In plain terms, subtract what you already have from the target, then divide the remainder by the number of deposits left. The max(0, …) part keeps the result from going negative. If your balance already meets or exceeds the target, the required contribution is $0 for that goal. Include these contributions when creating your monthly budget.
A few assumptions and limits apply:
- The target amount and current balance must use the same currency (here, US dollars).
- The number of remaining deposits must be a positive whole number to calculate a future contribution.
- The calculation assumes equal contributions and no interest, fees, withdrawals, or missed deposits.
- If no deposits remain and the target is not met, future deposits cannot close the gap by the deadline. You would need to consider an earlier contribution, a later deadline, a lower target, or another realistic source of funds.
Here is a second, separate illustration with three goals and nothing saved yet:
| Goal | Target amount | Current balance | Remaining monthly deposits | Required monthly contribution |
|---|---|---|---|---|
| Car maintenance | $900 | $0 | 9 | $100 |
| Holiday spending | $480 | $0 | 8 | $60 |
| Annual fees | $240 | $0 | 12 | $20 |
| Combined goals | $1,620 | $0 | Varies by goal | $180 total per month |
The $180 combined total assumes you fund all three goals at the same time and that each schedule fits its deadline. As each fund reaches its target, the monthly total drops. This table is a separate illustration from the one in the previous section, so do not add the two together.
To try your own numbers, use the calculator below. Enter your target, your current balance, and the number of deposits you expect to make. It shows the contribution you need and, if you enter what you plan to deposit, whether you would land short of or past your target.
Enter your goal to see how much to set aside at each deposit. The starting values are examples, so replace them with your own numbers.
Fix the highlighted entries to see your results.
- Amount still needed
- Required contribution per deposit
- Your planned contribution per deposit
- Projected balance at the deadline
This is a planning estimate, not a guarantee that you will reach your goal. It assumes equal deposits and excludes interest, fees, withdrawals, missed deposits, and changes to your target. Your entries are calculated in your browser and are not collected or sent anywhere.
Where Should You Keep Sinking Fund Money?
The right spot depends on how soon you need the money, how easily you can reach it, and how tempting it might be to spend. Fees matter too, so check an account’s terms before you commit. Common options include:
- A savings account or dedicated savings bucket. Simple and accessible. Some banks let you split a savings account into labeled buckets, so check whether yours does.
- A money market deposit account. The CFPB explains that banks and credit unions offer these accounts, that they tend to pay higher interest than other savings accounts, and that they usually limit the number of transactions by check, debit card, or electronic transfer. Some require a minimum deposit. They can work when those terms fit how you will use the money.
- A budgeting app or spreadsheet. You keep the money in an account you already have and track how much belongs to each goal. This avoids opening new accounts, but it takes discipline because the money sits where everyday spending happens.
- Cash envelopes. These can work for small goals if keeping cash is safe and practical for you. Cash can be lost, stolen, or destroyed.
If you are weighing deposit insurance, the details vary. Eligible deposits at an FDIC-insured bank are covered by FDIC deposit insurance, and eligible deposits at a federally insured credit union are covered by NCUA share insurance. The standard limit for each is $250,000, but coverage depends on the institution, the type of account, the ownership category, and the applicable limits. Some state-chartered credit unions use private insurance instead, so confirm your institution’s status.
A money market mutual fund is not the same as a money market deposit account. The CFPB describes mutual fund accounts as investments rather than savings or checking accounts, and the NCUA notes that it does not insure mutual funds. For money you need soon, stable and accessible options generally make more sense than stocks or other investments that can lose value.
What If You Cannot Afford to Fund Every Goal?
You do not have to fund everything at once. A few ways to adjust:
- Prioritize expenses that are essential or hard to postpone.
- Start with a smaller contribution you can sustain, even if it is below the full required amount.
- Look at discretionary spending for room, if there is any. Not everyone has extra to find.
- Extend a deadline when the expense and your circumstances allow.
- Revisit your estimates, and lower the target if a realistic lower-cost option exists.
- Avoid a contribution schedule you cannot keep up.
If your income does not cover your essentials, budgeting alone cannot close that gap. That is a limit of the method, not a personal failing.
Benefits and Limitations of Sinking Funds
The main benefits are practical. A sinking fund spreads a large cost across several pay periods, makes planned spending easier to manage, and can reduce the need to turn to credit for expenses you saw coming.
The limitations are just as real. Sinking funds take planning. Competing goals can add up to more than your budget allows, and actual expenses can come in higher than your estimates. They do not guarantee financial security or eliminate existing debt.
Start Your First Sinking Fund
Pick one upcoming expense, set a realistic target, and divide the amount you still need by the number of contributions you can make before it is due. That is the whole method.
Use the calculator earlier in this guide to turn your numbers into a contribution amount, then adjust the plan until it fits your budget. You can come back to it whenever a cost or a date changes.
Frequently Asked Questions About Sinking Funds
You can keep it for the next time the expense comes around, revise the target based on what you learned, or redirect it to another priority. The best choice depends on what the fund was for. Keeping it often makes sense for a recurring cost like an annual premium, while redirecting may suit a one-time purchase.