When Your Budget Needs a Reset
At some point, most budgets quietly stop matching real life. Your income may not have changed much, but somehow the spending drifted. A handful of subscriptions crept in. Convenience purchases started adding up in ways you didn’t fully track. The savings transfer you planned feels harder to execute than it did when you set it up. You’re not reckless with money; your budget simply became disconnected from how you actually live.
This is not a discipline problem. It’s a calibration problem, and the solution is a reset.
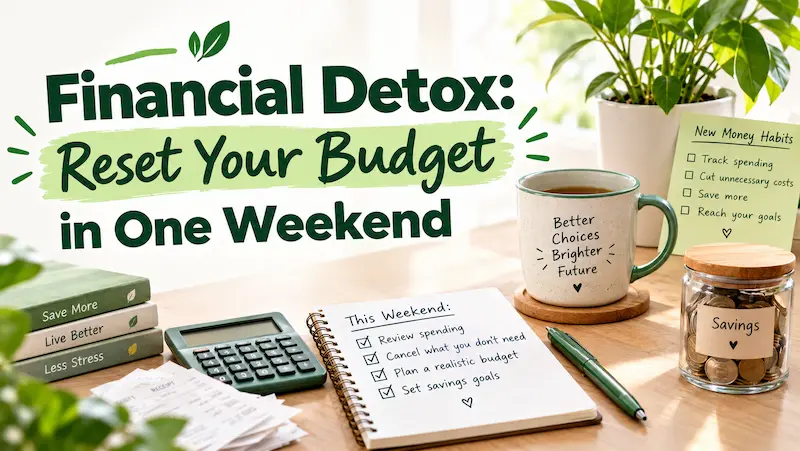
A financial detox is a structured weekend process for understanding where your money actually went, identifying spending that no longer earns its place, rebuilding your budget from the ground up, and giving whatever you free up a clear purpose. By Sunday evening, you should have a realistic budget grounded in actual income and actual spending, not an idealized version of one you made six months ago.
The process follows five stages:
SEE your spending clearly,
SORT it by what stays and what goes,
STOP unnecessary automatic charges,
RESET the budget using real numbers, and
REDIRECT the freed money toward something specific.
This is not a no-spend challenge. A financial detox is primarily diagnostic and rebuilding work. A brief spending pause may accompany it, but the pause is one component, not the goal.
What Is a Financial Detox?
A financial detox is a focused review of your current spending and budget. It gives you an accurate picture of where your money is going, helps you identify financial leakage, and produces a rebuilt budget that reflects your actual income, your actual obligations, and your actual priorities.
What a Financial Detox Helps You Do
- Understand what you actually spent over the past 30 days, rather than what you thought you spent
- Identify recurring charges you forgot about or no longer value
- Recognize spending patterns: convenience, impulse, habit, and subscription creep
- Separate expenses that reflect your priorities from those that don’t
- Rebuild the budget with realistic numbers, including expenses that don’t happen every month
- Assign freed-up money to a specific destination so it doesn’t simply disappear into untracked spending
What It Is Not
A financial detox is not a punishment. It is not an instruction to spend as little as possible. It will not solve serious structural financial problems on its own, and it won’t guarantee a specific outcome. If you cut $150 in discretionary spending but replace it with $150 in new discretionary spending, the budget has not improved. That distinction matters throughout this process.
Financial Detox vs. No-Spend Challenge vs. Budget Reset
| Financial Detox | No-Spend Challenge | Budget Reset | |
| Primary purpose | Diagnose spending and rebuild the budget | Reduce or eliminate nonessential purchases temporarily | Update the budget to reflect current income and expenses |
| Duration | One weekend, with 30-day follow-through | A defined period, often one week to one month | Ongoing, triggered by life changes |
| Main activity | Reviewing transactions, categorizing, and rebuilding | Behavioral spending restriction | Adjusting existing budget line items |
| Spending restrictions | Short pause on nonessentials | Core requirement | None required |
| Expected outcome | Realistic, rebuilt budget with intentional allocations | Behavioral reset, short-term spending reduction | Updated budget numbers |
A no-spend challenge focuses on the behavioral side: stopping purchases. A financial detox focuses on the structural side: understanding and rebuilding. The two are complementary rather than identical. SustainCents covers the no-spend challenge in a separate guide; if a structured behavioral restriction interests you after this weekend, that article goes deeper.
The 5-Step Financial Detox
The weekend is organized around five stages. Each builds on the one before it.
SEE: Pull your actual transaction history. Understand where the money went before making any decisions.
SORT: Divide spending into meaningful categories: essential, valuable, and low-value. Not all discretionary spending is wasteful.
STOP: Temporarily interrupt spending that doesn’t reflect your priorities. Cancel or pause subscriptions you’ve decided to cut. Create a short pause for nonessential purchases while you reassess.
RESET: Rebuild the budget using real take-home income, real fixed expenses, and realistic estimates for variable spending, including irregular costs that don’t appear every month. You can also use ChatGPT to create a monthly budget once you have those numbers organized.
REDIRECT: Assign the money you freed up to a specific purpose. Reducing spending and retaining those savings are two different steps.
Before You Start: Your 30-Minute Setup
Gather what you need before Saturday morning so the weekend stays on track.
Gather Your Financial Information
- Bank statements or transaction history for the past 30 days
- Credit card statements for the same period
- A list of recurring bills: rent or mortgage, utilities, insurance, phone, internet
- Any subscription or membership charges, including ones you’ve forgotten about
- Your current take-home income, meaning what actually arrives in your account after taxes and deductions
- Debt balances, minimum monthly payments, and interest rates if debt is a factor
- Any savings information you want to factor in
Most of this is available through your banking app or online account portal. The Consumer Financial Protection Bureau’s budgeting tools and resources offer additional structure if you’re building a budget from scratch.
Record Your Starting Numbers
Before the weekend begins, write down three figures: current monthly take-home income, your best estimate of what you spent last month, and your current savings allocation. These become your baseline for the reset.
Write Down Your Three Biggest Money Concerns
Be specific. “I spend too much” is not actionable. “I can’t seem to accumulate savings despite my income” is. “I have recurring charges I think I’m no longer using” is. Starting with a concrete concern helps you know what to look for.
Saturday Morning: See Where Your Money Went
Step 1: Review Your Last 30 Days of Transactions
Pull every transaction from the past 30 days. Don’t filter anything yet. Look at the full picture and avoid the common mistake of cutting spending before you know where it’s going.
Most people find at least one surprise. Not because they’re careless, but because a significant portion of modern spending happens automatically and gets reviewed rarely, if ever. The Federal Reserve’s Report on the Economic Well-Being of U.S. Households consistently documents that many Americans struggle with financial cushion despite having regular income. Invisible spending is one of the reasons: recurring charges, convenience purchases, and subscription accumulation add up without ever prompting a decision.
This step makes it visible again.
Step 2: Look for Patterns, Not Just Individual Purchases
Individual transactions can be misleading. What you’re looking for is the shape of your spending over a month.
Look for recurring charges you don’t remember setting up. Look for categories that cost more than you expected: restaurants, grocery stores, delivery services, convenience purchases. Look for subscriptions across streaming, software, cloud storage, apps, fitness platforms, and subscription boxes. The CFPB’s consumer tools include useful guidance on managing recurring charges.
Also notice the context behind spending. Is a significant portion of your food budget driven by convenience rather than preference? Are purchases clustered around specific situations, like stress, boredom, or a particular time of day? That context matters when you decide what to change.
This is information, not judgment.
Saturday Afternoon: Sort the Spending That Stays and the Spending That Goes
Once you’ve seen the full picture, sort it. Three categories cover most situations.
Essential: Expenses required for basic obligations and needs. Rent or mortgage, utilities, insurance premiums, minimum debt payments, groceries, and transportation necessary for work.
Valuable: Discretionary spending that genuinely provides meaningful value relative to its cost. A gym membership you use consistently. A streaming service your household watches regularly. A professional tool that supports your income. A dinner out that you actually looked forward to.
Low-Value: Spending that does not provide enough value relative to its cost. Subscriptions you barely open. Convenience spending driven by habit rather than choice. Duplicate services. Recurring charges you forgot were still active.
The key point: discretionary does not automatically mean wasteful. The question is not whether a purchase is optional. It’s whether it’s earning its place.
Audit Your Subscriptions
Go through every recurring charge and ask three questions: Do I actually use this? Would I notice if it were gone? If it’s for occasional use, is the cost proportionate to how often I use it?
Some subscriptions are easy calls. Others are genuinely uncertain. That uncertainty is itself useful information: if you’re not sure whether you value a service after paying for it for months, that’s a signal worth acting on.
Identify Your Three Biggest Opportunities
You don’t need to find 20 things to cut. Identify the three places where a realistic change would have the most meaningful financial impact. A $30 subscription you don’t use and a $15 recurring delivery fee you pay on autopilot are worth catching. But if the real opportunity is a $200 monthly charge you can reduce or eliminate, that deserves the most attention.
Prioritizing a few meaningful changes produces better results than trying to optimize every line item at once.
Saturday Evening: Stop Automatic Spending
This is not a full no-spend challenge. It’s a short interruption designed to create deliberate space between habit and choice.
Continue Paying for Essentials
Do not stop necessary bills, mortgage or rent, required debt minimums, insurance, or utilities. Interrupting essential payments creates problems that cost more to resolve than the interruption saves.
Temporarily Delay Nonessential Purchases
For the rest of the weekend and the first week following, pause nonessential purchases you had been planning. Not indefinitely: just pause them. Write them down.
Create a “Buy Later” List
When something nonessential comes up during the detox weekend, add it to a list rather than purchasing it. At the end of the process, revisit the list. Some items will still feel necessary. Others will feel less urgent. The waiting period reveals which is which. For items you still need, consider whether you can get them without buying.
Sunday Morning: Reset Your Budget
The rebuilding work starts here.
Start With Actual Take-Home Income
Use your actual take-home income, meaning what arrives in your account after taxes and deductions, not your gross salary. If your income varies month to month, use a conservative recent average rather than your best month.
Add Fixed Expenses
Fixed expenses are obligations that stay roughly the same each month: rent or mortgage, car payment, insurance premiums, loan minimums, any subscriptions you’ve decided to keep. List them individually.
Add Variable Essentials
Variable essentials are needs whose amounts change but whose necessity doesn’t: groceries, utilities, fuel or transit, household supplies. Use your actual transaction history to estimate these, not what you hope they are.
Allocate the Remaining Money
Whatever remains after fixed and variable essentials needs intentional assignments. Unallocated income doesn’t automatically become savings. It becomes untracked spending. Every dollar benefits from a destination: discretionary spending, savings, irregular expenses, debt repayment, or a specific financial goal.
Sunday Midday: Budget for Expenses That Don’t Happen Every Month
One of the most reliable reasons a realistic budget fails in practice is the irregular expense problem. Car registration. Annual insurance renewals. Holiday spending. Medical appointments. Back-to-school costs. These are predictable. They simply don’t arrive monthly.
If your budget doesn’t account for them, they show up as emergencies even when they are anything but.
The approach is straightforward: estimate the annual total of a predictable expense, then divide by 12.
For example: a $600 annual car insurance renewal divided by 12 months comes to $50 per month. That $50 can accumulate in a dedicated savings account or a named sinking fund. When the bill arrives, the money is ready.
Work through your own list of predictable irregular costs. The FDIC’s Money Smart financial education program includes practical tools for building these categories into a working budget.
Sunday Afternoon: Decide What to Keep, Reduce, or Cut
With a rebuilt budget in front of you, go through discretionary and variable expenses and make a clear decision for each.
Keep: The expense is providing real value. Leave it unchanged.
Reduce: The category is worth keeping, but the amount can come down. Eating out less frequently rather than eliminating it. Switching to a lower tier of a service you still use.
Cut or cancel: The expense isn’t providing enough value to justify its cost. Remove it.
The goal is alignment, not deprivation. A budget that eliminates every enjoyable purchase is a budget that won’t hold past the first few weeks.
What You Should Not Cut Just to Balance the Budget
Be careful here. Removing health insurance to reduce monthly costs, skipping minimum debt payments to redirect cash, or cutting food spending below a realistic amount can create larger and more expensive problems. A budget that balances on paper but fails your actual life isn’t a useful budget.
Sunday Afternoon: Run a Budget Reality Check
Before committing to the rebuilt budget, test it against a few honest questions.
- Does planned spending actually fit your take-home income?
- Are essential expense estimates realistic, based on actual spending rather than optimistic guesses?
- Have you included irregular expenses?
- Are all minimum debt payments included?
- Is the savings allocation achievable without cutting into essentials?
- Is there room for reasonable discretionary spending?
- Does the budget reflect how you actually live?
When I review a budget, I don’t start by looking for something to cut. I start by asking whether the plan is honest. An aggressive savings target looks impressive until it requires you to pull the money back every other month.
If Debt Is Your Biggest Financial Problem
If debt repayment is the priority your detox reveals, start by organizing what you owe clearly: balances, interest rates, minimum payments, due dates, and any fees. That picture tells you what you’re dealing with before you decide how to address it.
Two common approaches:
Debt avalanche: Direct additional payments toward the highest-interest balance first. This approach minimizes total interest paid over time and is typically the most mathematically efficient strategy.
Debt snowball: Direct additional payments toward the smallest balance first. Paying off smaller accounts provides a sense of momentum that some people find motivating.
Each approach involves trade-offs. The avalanche reduces total cost. The snowball may sustain motivation through visible progress. The right choice depends on your interest rate differences, your available cash flow, and what actually keeps you on track over months rather than weeks. Neither method is universally superior, and the best strategy is the one you’ll follow consistently.
Sunday Evening: Redirect the Money You Freed Up
A spending reduction is not the same thing as savings.
If you cut $200 in monthly subscriptions and discretionary spending, but that $200 drifts into other untracked spending, your financial position hasn’t changed. The reduction needs a specific destination to produce a different outcome.
Possible destinations:
- A savings account or emergency fund
- An additional payment toward a high-interest debt, beyond the minimum
- An irregular expense fund for predictable annual costs
- A specific financial goal with a defined timeline
- A retirement contribution if that category has been underfunded
Assign it now, before the weekend ends. That decision becomes much harder once the money is already mixed into general spending.
What a Before-and-After Budget Reset Looks Like
The figures below are illustrative examples only. They don’t represent an ideal budget for any reader or a recommended allocation.
| Category | Before | After |
| Take-home income | $4,000 | $4,000 |
| Essential expenses | $2,400 | $2,400 |
| Discretionary spending | $900 | $600 |
| Irregular expenses | $0 (unplanned) | $300 |
| Savings | $200 | $500 |
| Debt or financial goal | $0 | $200 |
| Unplanned spending | $500 | $0 |
The “before” scenario is common. The $500 in unplanned spending wasn’t intentional; it was simply unassigned money that moved without direction. The “after” scenario doesn’t cut total spending by $500. It assigns that money deliberately, including to irregular expenses that previously arrived as surprises. The total outflow is the same; the clarity is different.
How Much Can a Financial Detox Save?
The honest answer is: it depends on what you find, what you change, and whether the freed money actually stays redirected.
A simple calculation:
Current monthly discretionary spending minus new planned monthly discretionary spending = potential monthly spending reduction.
Potential monthly spending reduction multiplied by 12 = potential annual spending reduction.
That number represents a reduction in planned spending. It is not a guaranteed savings figure. Actual savings depend on whether you retain and redirect the money, or whether it migrates into different spending categories. Reducing planned spending and retaining those savings are two distinct steps that both have to happen.
Financial Detox Calculation Worksheet
| Amount | |
| Current monthly take-home income | $ |
| Current monthly fixed expenses | $ |
| Current monthly variable essentials | $ |
| Current monthly discretionary spending | $ |
| New planned monthly discretionary spending | $ |
| Monthly spending reduction | $ |
| Amount redirected to savings | $ |
| Amount redirected to debt repayment | $ |
| Amount allocated to irregular expenses | $ |
| Potential annual spending reduction (x12) | $ |
Your 30-Day Financial Reset Plan
The weekend produces the plan. The next 30 days test it.
Week 1: Observe. Track actual spending against the new budget without making adjustments yet. The point is to see whether your estimates hold before changing anything.
Week 2: Adjust. Identify where the plan was unrealistic. A grocery estimate that was too low needs to come up, funded from somewhere else in the budget. Adjusting is not failure; it’s how a plan becomes accurate.
Week 3: Automate. Where it makes sense, automate transfers. A savings contribution that happens automatically on payday doesn’t require a decision every month. The same logic applies to additional debt payments if that’s part of your plan.
Week 4: Review. Compare what you planned against what happened. The gap between the two tells you what still needs refinement.
Choose Three Rules for the Next 30 Days
Keep these specific to your situation. For example: review all transactions once a week rather than letting them accumulate, wait 48 hours before any unplanned purchase above a threshold you choose, or cook at home for a set number of dinners per week instead of ordering delivery. Rules that fit how you actually live are the ones that last past the first week.
What If You Go Over Budget?
You probably will at some point. The useful response is four steps.
Notice: Identify where the overage happened and by how much.
Understand: Determine why. Was the budget estimate unrealistic from the start? Was it a one-time event? Was it a recurring pattern you didn’t account for?
Adjust: Change the plan to reflect reality, not just intent. A budget that consistently requires you to overspend in a category isn’t calibrated correctly.
Continue: Don’t treat one difficult week as evidence that the system doesn’t work.
Going over budget is information. The goal is to understand what happened, not to abandon the whole rebuilt structure.
Financial Detox Weekend Checklist
Before You Start
- [ ] Gather 30 days of bank and credit card statements
- [ ] List all recurring bills and subscriptions
- [ ] Record current take-home income
- [ ] Note debt balances and minimum monthly payments
- [ ] Write down your three biggest financial concerns
Saturday
- [ ] Review all transactions from the past 30 days
- [ ] Identify spending patterns and recurring charges
- [ ] Sort spending into essential, valuable, and low-value
- [ ] Audit subscriptions for actual usage
- [ ] Identify three biggest opportunities for meaningful change
- [ ] Pause nonessential purchases; start the “buy later” list
Sunday
- [ ] Rebuild the budget starting from actual take-home income
- [ ] Add fixed and variable essential expenses
- [ ] Estimate and account for irregular annual expenses
- [ ] Decide what to keep, reduce, or cut
- [ ] Redirect freed money to a specific destination
- [ ] Complete the reality check
- [ ] Write out the 30-day follow-through plan
When Should You Do Another Financial Detox?
There’s no universal schedule. A few situations are useful signals.
Your income changed significantly, in either direction. A major fixed expense shifted: housing, a car, insurance. You’ve accumulated new debt or paid off existing debt. Your household or living situation changed. You’ve noticed your actual spending drifting away from your plan for several months running. A significant financial goal, such as a home purchase, a major expense, or retirement, has moved meaningfully closer.
A full reset isn’t necessarily an annual requirement. A lighter monthly review of transactions can catch drift early, before it becomes a weekend project.
Reset, Don’t Restrict
The financial detox isn’t about building a punishing budget you endure until discipline runs out. It’s about understanding what your money actually did, comparing that to what you want it to do, and building a realistic plan that connects the two.
SEE what happened. SORT it honestly. STOP the spending that isn’t earning its place. RESET the budget using real numbers. REDIRECT the money you free up toward something that matters.
That last step is the one that creates a different outcome rather than a temporary restriction followed by a drift back to where you started. Spending less only improves your financial position if the money goes somewhere intentional. Cutting a subscription and replacing it with a different one of the same cost isn’t a reset; it’s a substitution.
At SustainCents, we approach money through the same lens we bring to consumption generally: cost, usefulness, frequency, and actual value over time. Financial waste and material waste can come from similar habits, particularly autopilot and accumulation that outpaces actual use. A financial detox asks the same question that thoughtful purchasing habits ask: is this still adding enough value to justify its continued place in the budget?
The weekend gives you the clearest possible answer to that question. What you do with it is the part that lasts.
Financial Detox FAQs
A financial detox is a structured process for reviewing your actual spending, identifying financial leakage, and rebuilding your budget from real numbers rather than assumptions. It typically takes one focused weekend to complete, followed by 30 days of follow-through.