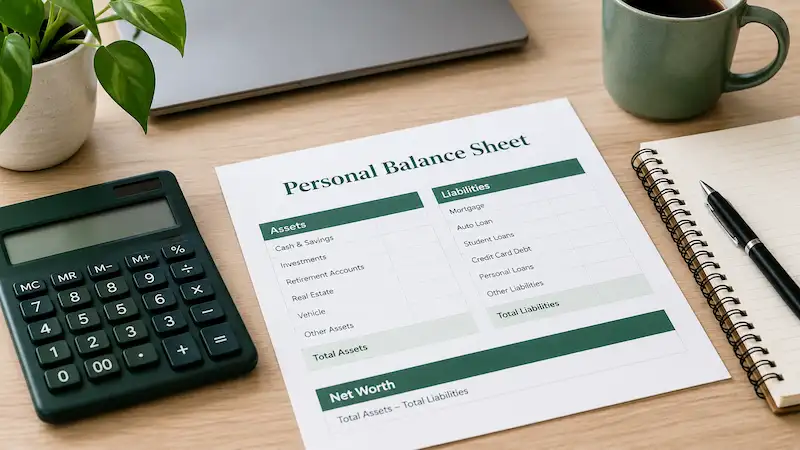
Most people know their paycheck and their rent, but far fewer could say what they own and owe on a given day. A personal balance sheet fixes that. It’s a snapshot that lists your assets (what you own), your liabilities (what you owe), and the gap between them, your net worth, as of one specific date.
The formula is short:
Net Worth = Total Assets − Total Liabilities
This guide covers what belongs on each side of the statement, a five-step process for building one, and two hypothetical examples, one with positive net worth and one with negative. It also explains how to value a home, car, or retirement account, how net worth differs from cash you can spend, and how to set up a spreadsheet in Excel or Google Sheets so you can update it over time.
What Is a Personal Balance Sheet?
A personal balance sheet is a statement of what you own, what you owe, and what remains, measured on a single date. The Federal Reserve Bank of Dallas defines a balance sheet as a snapshot of assets, liabilities, and net worth on a given date, and the SEC’s Investor.gov uses the term net worth statement for the personal version.
- Assets are things you own that have value, such as cash, investments, and property.
- Liabilities are debts, meaning the balances you currently owe.
- Net worth is what’s left after you subtract liabilities from assets.
Because it’s a snapshot, a balance sheet doesn’t show what you earned or spent over a month or year. A budget or cash flow tracker does that. It also differs from a business balance sheet: you don’t need double-entry bookkeeping to make a useful personal one, only accurate balances and reasonable estimates.
Net Worth = Total Assets − Total Liabilities Total Assets = Total Liabilities + Net Worth
Both lines say the same thing. Net worth can be positive (assets exceed liabilities), zero, or negative (liabilities exceed assets), as Investor.gov explains.
What Goes on a Personal Balance Sheet?
Assets: What You Own
Record each asset at a reasonable current value on your statement date, not at what you paid for it. Common categories include:
- Cash, checking accounts, and savings accounts (including money market accounts and CDs)
- Investment and retirement accounts, such as brokerage accounts, 401(k)s, and IRAs
- Real estate, including a home you own
- Vehicles
- Significant personal property, such as jewelry, collectibles, or equipment, when you can estimate a realistic resale value
The Department of Labor’s Savings Fitness balance sheet worksheet groups assets in a similar way and is a useful reference for categories.
Liabilities: What You Owe
List what you owe today: mortgage balances, auto loans, student loans, credit card balances, personal loans, home equity loans, and other outstanding debts such as unpaid medical bills. Use the outstanding balance on your statement date. Don’t use the original loan amount, and don’t use the total of all future scheduled payments, which includes interest you haven’t incurred yet.
Net Worth: What Remains After Debts
Net worth is the difference between your assets and your liabilities. It isn’t money you can spend. Much of it may sit in a home or a retirement account, which can’t be turned into cash quickly or without cost. The Dallas Fed’s glossary describes liquidity as the ease of converting an investment into cash. Your liquid assets, such as checking and savings, are only part of your net worth, and the cash you can actually spend this month is smaller still, since upcoming bills come first.
What Should You Include, Estimate, or Leave Out?
Include any asset or debt large enough to change your totals noticeably. Estimate where you must, and mark which figures are estimates, because a home or vehicle value is an opinion until a sale happens. The Department of Labor’s worksheet page says guessing is okay and you can refine the numbers later, so don’t wait for perfect records.
Count each item once. If you list your home at its market value, list the mortgage as a liability; don’t list only the equity and also subtract the loan. A simplified worksheet can skip everyday items that are hard to value, such as clothing and ordinary furniture. A lender asking for a financial statement may want more detail and its own format, so follow its instructions if you’re applying for credit.
How to Make a Personal Balance Sheet in 5 Steps
Step 1: Choose a Date for Your Financial Snapshot
Pick one date, such as the last day of a month or quarter. Balances move daily, so a checking balance from March, a loan balance from June, and a home estimate from last year produce a number that describes no real moment. A consistent date also makes future snapshots comparable.
Step 2: Gather Your Financial Records
Pull your latest statements for bank accounts, brokerage and retirement accounts, mortgages, auto and student loans, and credit cards. For a home or vehicle, gather a reasonable market-value estimate. The Department of Labor’s financial documents checklist lists the typical records. Use account nicknames such as “credit union savings” and leave account numbers and other identifying details off the sheet.
Step 3: List and Total Your Assets
Give each asset its own line with a category, a short description, and a value. For jointly owned assets, enter only your share, and apply the same share to any debt secured by that asset. Add the values to get total assets.
Step 4: List and Total Your Liabilities
Give each debt its own line with the current balance. Include debts that are easy to forget, such as medical bills, personal loans, or money owed to family. Add the balances to get total liabilities.
Step 5: Calculate and Check Your Net Worth
Subtract total liabilities from total assets. For example, if assets total $60,000 and liabilities total $45,000, net worth is $60,000 − $45,000 = $15,000. (That’s a simple illustration; the next section has full examples.)
Before you trust the result, check for:
- Duplicates: an account listed under two categories
- Omitted debts: a card, loan, or bill you didn’t record
- Mixed dates: balances pulled from different days
- Formula errors: totals that skip a row or double count one
Personal Balance Sheet Examples: Positive and Negative Net Worth
Both examples below are hypothetical illustrations dated October 1, 2026. They aren’t actual household records. In each, the household owns everything listed in full and owes the related debts in full.
Example 1: A Household With Positive Net Worth
| Asset | Value |
|---|---|
| Checking and savings | $12,000 |
| Retirement accounts | $35,000 |
| Home | $280,000 |
| Vehicle | $18,000 |
| Total assets | $345,000 |
| Liability | Balance |
|---|---|
| Mortgage | $230,000 |
| Auto loan | $10,000 |
| Credit card debt | $3,000 |
| Total liabilities | $243,000 |
Net worth: $345,000 − $243,000 = $102,000.
This is a household-level statement, and the $102,000 isn’t cash to spend. The household holds $12,000 in checking and savings. The rest is home value, retirement accounts, and a vehicle, each with different access conditions, possible costs, and time horizons. Selling a home involves transaction costs and finding another place to live, and retirement withdrawals can involve taxes and penalties. These numbers alone also can’t show whether the household is financially secure, because income stability, expenses, and insurance matter too.
Example 2: A Renter With Negative Net Worth
| Asset | Value |
|---|---|
| Checking and savings | $2,500 |
| Retirement accounts | $7,500 |
| Vehicle | $8,000 |
| Total assets | $18,000 |
| Liability | Balance |
|---|---|
| Student loans | $24,000 |
| Auto loan | $7,000 |
| Credit card debt | $2,000 |
| Total liabilities | $33,000 |
Net worth: $18,000 − $33,000 = −$15,000.
The listed liabilities exceed the listed assets by $15,000. That’s a measurement on one date, not a moral judgment and not a prediction. The statement doesn’t show income, whether balances are falling, or what the loan terms are.
Notice how each example treats ownership. Every vehicle appears at full value alongside its full loan balance, and the home sits beside its full mortgage. If you co-own an asset, apply the same ownership share to the asset and to its loan.
How to Value Assets on Your Personal Balance Sheet
Home and Real Estate
Use a reasonable estimate of current market value, such as recent sale prices of comparable nearby homes, rather than the purchase price. Record the outstanding mortgage separately as a liability. The Dallas Fed’s own example is a $120,000 home with an $80,000 mortgage, which leaves $40,000 in equity that counts toward net worth. Equity isn’t spendable cash until you sell or borrow against it, and both carry costs.
Cars and Other Vehicles
Use a realistic resale value, based on what comparable vehicles with similar mileage sell for. The Dallas Fed notes that a car loses value quickly, so last year’s figure may be too high. Keep the loan separate: an $18,000 car with a $10,000 loan is an $18,000 asset and a $10,000 liability.
Retirement Accounts and Investments
Use the balance shown on your statement as of the snapshot date. Market prices fluctuate, so the figure will differ a week later. Withdrawals from traditional 401(k)s and IRAs are generally taxable, and early withdrawals can carry penalties. Pick one approach, such as the reported balance, and use it every time.
Personal Property and Other Assets
Include significant items only when you can estimate a realistic resale value, for instance from recently sold listings of comparable items. Skip ordinary belongings. These are informal estimates, not certified appraisals, and a lender or insurer may require a professional one.
Valuation checklist
- Use values from the same statement date.
- Base estimates on current comparable prices, not purchase prices.
- Apply the same ownership share to an asset and its debt.
- Count each item once, and list each loan separately from the asset it financed.
What Should You Do If Your Net Worth Is Negative?
A negative result describes one date, not your future. Investor.gov says a negative net worth shouldn’t be discouraging and that following a financial plan can help. Practical next steps:
- Confirm the figures. Recheck balances, estimates, and dates, and look for missing assets such as an old retirement account from a previous employer.
- List every debt with its balance, interest rate, and minimum payment. The Department of Labor’s debt reduction worksheet uses this layout and notes that paying the highest-rate debts first is a common approach, though clearing a small balance can also simplify things.
- Compare income, essential expenses, and minimum payments to see how much room you have.
- Consider a cash reserve for essentials before directing every spare dollar to debt, so one unexpected bill doesn’t go back on a card. The right size depends on your circumstances.
- Track balances over time using the same method each time.
Net worth can improve through paying down debt, growing assets, or both. The right mix depends on your situation.
Personal Balance Sheet vs. Budget vs. Cash Flow Statement
| Tool | Main purpose | What it tells you |
|---|---|---|
| Personal balance sheet | Measures financial position on a specific date | What you own, what you owe, and your net worth |
| Budget | Plans income and spending over a period | How you intend to allocate your money |
| Cash flow statement or tracker | Records money coming in and going out over a period | Where money comes from and where it goes |
These tools complement each other. The Department of Labor’s Savings Fitness set, for example, treats the balance sheet and the cash flow spending plan as separate worksheets.
A positive net worth doesn’t mean you have enough cash for next month’s bills. Someone with substantial home equity and retirement savings can still be short when rent comes due. A balanced budget doesn’t prove your debt is shrinking either, since you can cover every bill while balances stay flat. Comparing balance sheets over time shows the direction of your assets and debts, and cash flow tracking helps explain why.
Free Personal Balance Sheet Template for Excel and Google Sheets
You can set up a working template in either program with this layout.
- Summary sheet: a labeled statement date in B1 (input), then total assets (B3), total liabilities (B4), and net worth (B5).
- Assets and Liabilities sheets: one table each, with headers in row 5 and entries starting in row 6. Columns: Category, Description, Value (or Balance), Your share (%), Counted amount, Notes.
- Formulas: in each Counted amount cell, =IF(C6=””,0,C6*IF(D6=””,1,D6)). On the Summary sheet, B3 =SUM(Assets!E6:E205), B4 =SUM(Liabilities!E6:E205), and B5 =B3-B4.
Shade input cells one color and formula cells another. The share column handles joint ownership: enter the same percentage on an asset and on its loan. Leave the extra blank rows inside the sum range so new entries are included automatically.
To update, change the date, refresh each balance, and add rows inside the range. After building the sheet, test it: change a value, add a row, leave cells blank, and try totals that produce positive, zero, and negative net worth.
If you’d rather start from an existing form, the Dallas Fed’s Learn the Language page offers a blank balance sheet in spreadsheet and PDF formats, and the Department of Labor provides an online balance sheet worksheet.
How Often Should You Update a Personal Balance Sheet?
Investor.gov suggests updating a net worth statement every year. A quarterly review is a practical starting point for many households that want to see change sooner. Monthly updates can help if you’re actively paying down debt or tracking a major change.
Update outside your schedule after buying or selling a home, taking on a major loan, or a significant change in your investments. Whatever the schedule, keep your valuation methods consistent so each snapshot is comparable. Daily or weekly updates aren’t necessary for most people.
Conclusion
Knowing your total assets, total liabilities, and net worth gives you a fixed point to measure from. You don’t need perfect records to start. A first snapshot built on reasonable estimates is more useful than a precise one you never finish. Set up the template layout above, enter today’s balances, and note which values are estimates. Then review it periodically with the same method, so each change you see reflects your finances rather than shifting assumptions.
Frequently Asked Questions
Net worth equals assets minus liabilities, which is the same as saying assets equal liabilities plus net worth. Since net worth is the leftover amount, the equation holds by arithmetic. The real check is whether your totals match your line items and whether any account is duplicated or missing. A mismatch usually points to a data-entry, formula, or calculation error.